



Renting Out Property in North Cyprus: Tax, Licences, Management
Renting out property in North Cyprus (the Turkish Republic of Northern Cyprus, TRNC) falls under two quite different sets of rules, depending on how long a guest stays. A tourist stay of up to 60 days, counting the day of arrival and the day of departure, is a holiday-house letting under the Holiday Houses Law, Law 54/2025, which has applied since 1 March 2026 and requires a registration certificate and an operating permit from the Tourism Planning Department. Anything longer is an ordinary tenancy, where the main public-law burden is a 10% income-tax withholding on gross rent. All rules, rates and prices in this guide are stated as of 24 October 2026.
This guide sets out what the TRNC texts say about long-term and holiday letting: the registration steps and their fees, the standards a holiday home must meet, the income-tax mechanism with worked arithmetic, stamp duty, VAT and other costs, the tenancy law that applies in declared control areas, and the tenant groups an owner is likely to meet, including students in Famagusta. It also reads the rental programmes and “rental guarantee” lines that developers print on their project pages, using the listings on our site as examples, and it explains why none of those lines can be turned into an income figure without the signed contract. Rules that depend on a Council of Ministers decree are marked as such.
Renting Out Property in North Cyprus: Key Facts at a Glance
| Question | Position on 24 October 2026 | Basis |
|---|---|---|
| What counts as a holiday-house letting? | A lease for tourism purposes that does not exceed 60 days, arrival and departure days included, of a unit built as housing | Holiday Houses Law 54/2025, art. 2 |
| Who regulates holiday lets? | The Tourism Planning Department of the Ministry responsible for tourism | Holiday Houses Law, arts. 2 and 14 |
| What must an owner hold before the first guest? | A registration certificate (Sicil Belgesi) and an operating permit (Isletme Izni Belgesi); the permit lasts one year and is renewed every year | Holiday Houses Law, arts. 7-9 |
| In force since | 1 March 2026; existing operators had four months from that date to comply | Holiday Houses Law, art. 21 and transitional art. 1 |
| Income tax on rent | 10% of gross rent, including advance rent, furnished or unfurnished; final tax for individuals | Income Tax Law, art. 31(6), text consolidated 25 May 2026 |
| VAT on renting immovable property | 0% (Schedule I of the VAT regulation) | VAT regulation, updated 7 October 2026 |
| Stamp duty on a lease | Taxed as an agreement on the total fixed-term rent; the tenant pays unless the parties agree otherwise | Stamp Duty Law 19/1963, as consolidated |
| Tenant protection law | Rent (Control) Law 17/1981 applies only in areas the Council of Ministers declares control areas | Rent (Control) Law, art. 3 |
| Foreign-purchase limits that cap how many units a foreigner may own | Set by Decree-Law 89/2026 (Resmi Gazete 147, 7 August 2026); its 90-day validity ends about 5 November 2026 unless Parliament enacts it | Resmi Gazete No. 147 |
Two cautions run through the rest of the guide. First, the holiday-home regime is new: its text was passed by Parliament on 24 November 2025 and the digital registration system was reported as launched in July 2026, so practice at the Department may differ in detail from the text. Second, tax law and tenancy law look at the contract and the money flow, not at how a developer labels a product, so a marketing phrase such as “rental programme” does not by itself change which rules apply.
Which Rules Apply to Renting Out Property in North Cyprus: Long-Term or Holiday Let
The Holiday Houses Law defines a “short-term letting” by length alone. A lease or agreement between owner and user for tourism purposes counts as short-term if it does not exceed 60 days, counting both the day the user takes the home and the day the user leaves. A “holiday house” is an independent accommodation unit built as housing, with a kitchen that lets the user cook, where the owner is not obliged to supply extra services beyond the items the law and its regulations require; hotels and tourist facilities are outside it. On those definitions, a one-week stay and a 45-day winter stay are holiday lets, while a semester-long student let or a one-year tenancy is not.
The housing itself must qualify. The Law defines a “dwelling” as an independent unit built as housing under the planning rules and approved as housing under the Roads and Buildings Regulation Law, or recorded as housing at the Land Registry, or described as housing in a sale contract deposited at the Land Registry. It lists five types that can become holiday houses: villa, detached house, studio flat, apartment and residence flat. A residence flat is an apartment inside a gated complex with amenities such as a pool, spa, sauna, Turkish bath, gym, bar or restaurant and a high level of guarding.
| Feature | Holiday let (up to 60 days) | Longer tenancy |
|---|---|---|
| Public registration | Registration certificate and annual operating permit from the Tourism Planning Department | None under the Holiday Houses Law |
| Guest or tenant records | Signed user registration form for every stay; two copies sent to the Department each month | Lease contract; stamping at the Tax Department |
| Income tax on the rent | 10% of gross rent under art. 31(6), unless the property is part of business accounts (art. 31(6)(D)) | 10% of gross rent, final for individuals |
| VAT | Renting immovable property is on the 0% schedule; accommodation services linked exclusively to tourism appear on the 5% schedule | 0% |
| Tenant protection and eviction | The Law lets the owner remove an overstaying user, with an exception where a written contract proves a later date | Rent (Control) Law 17/1981 where the property lies in a declared control area |
| Penalties for breach | Notice, fine, suspension, sealing, criminal fine | Contract remedies and the tax rules |
The VAT row needs a word of explanation. The VAT regulation consolidated on 7 October 2026 lists “all kinds of immovable property rental services” on the 0% schedule, and lists accommodation services related exclusively to tourism activities on the 5% schedule. The regulation does not mention holiday houses, so which entry covers a particular holiday-home stay is a classification that the Tax Department applies to the facts. The Holiday Houses Law itself states that one of its aims is to let the state collect every tax, duty, fee and similar revenue due on holiday lets, which is why VAT and income-tax treatment is worth settling with an accountant registered in the TRNC before the first booking.
Holiday Houses Law 54/2025: Registration and Operating Permit
The Holiday Houses Law was passed by Parliament by majority vote on 24 November 2025, according to Kıbrıs Gerçek, and the Deputy Prime Minister and Tourism Minister described its purpose as registering the homes, tracking their income and making tourist numbers measurable. Opposition members criticised the bill as rushed and warned about competition for small hotels, so the political debate around it was not unanimous. The text on the Central Legislation Office site carries the number 54/2025 and states that it enters into force on 1 March 2026. A transitional article gave anyone already running a holiday home on that date four months to bring it into line with the Law, and failure to do so exposes the operator to the Law’s sanctions.
For renting out property in North Cyprus on a tourist basis, an owner, an attorney acting under a proper power of attorney, or a “lessor” must apply to the Department for a register entry and certificate before running a holiday home. The definition of lessor is wide: it includes a person or partnership authorised in writing by the owner to let on the owner’s behalf, and a person or company that, with the owner’s written consent, registers the owner’s dwellings under its own name and runs them as holiday homes. The definition of “owner” includes a buyer named in a sale contract deposited at the Land Registry, not only the holder of a title deed. A single application form can cover several units, and the Department may require applications through an electronic portal. Yorum Kıbrıs reported on 24 July 2026 that a Holiday Homes Digital Management System had been introduced to take registration, licensing and inspection online, and that holiday-home companies and Turkish and foreign individuals could open accounts and upload documents.
| Step | Time limit in the Law | Fee (percentage of the monthly gross minimum wage) | Amount at the January 2026 wage of TL 60,618 |
|---|---|---|---|
| 1. Apply with form and documents | Missing items must be supplied within 15 working days or the application is treated as not made | None at this stage | None |
| 2. Department inspects the unit | Within 30 working days of a complete application | None | None |
| 3. Decision in writing | Within 90 working days of the application | None | None |
| 4. Registration certificate issued | Within 10 working days of the register entry, against payment | 50%, one-off | TL 30,309 (about GBP 455) |
| 5. Operating permit issued | Within 10 working days of paying the certificate fee | Per unit: 7% standard, 11% comfortable (renewal rate), 15% top class | TL 4,243 / 6,668 / 9,093 (about GBP 64 / 100 / 136) |
| 6. Renewal each year | Apply within the 30 working days before the permit expires; decision within 30 working days | Same per-unit percentages | As in step 5 |
| Adding units later | Change of register and certificate | 10% for the change, plus the permit fee for each new unit | TL 6,062 (about GBP 91) for the change |
| Dropping some units | Application for deregistration | 5% | TL 3,031 (about GBP 45) |
The fees are written as shares of the gross monthly minimum wage “in force at the start of the year”. The minimum wage from 1 January 2026 is TL 60,618, according to the Cyprus Turkish Chamber of Commerce notice that cites the Resmi Gazete of 23 January 2026; the Tax Department’s page gives the later rate of TL 70,893 gross from 1 July 2026, which applies to fines but not to these fees. Sterling equivalents in this guide use the Central Bank’s effective selling rate of 66.6323 lira per pound, valid for 24-26 October 2026. Worked out, the one-off certificate fee is 60,618 x 50% = TL 30,309, and 30,309 / 66.6323 = about GBP 455. A standard-class permit is 60,618 x 7% = TL 4,243.26, or about GBP 64 a year per unit. The first-year permit clause and the renewal clause use the same percentages for the standard and top classes; the renewal clause is the one that gives the comfortable class as 11%, and that is the figure used above.
The Law divides holiday homes into standard, comfortable and top-class (lüks in the Turkish text) according to the services, furniture, equipment and installations that the Department finds on inspection. The class is recorded next to the address on the register entry and on the permit, and the classification procedure is left to a regulation to be approved by the Council of Ministers. Documents attached to the application form include a copy of the title (koçan) of the unit or the property it stands on, a copy of the final approval certificate that allows the home to be occupied, a copy of the registered sale contract where there is one, identity cards, and company documents where a company applies. Where the lessor is not the owner, the form asks for the owner’s written consent certified by a notary-type officer (tasdik memuru) plus the same property documents.
Two features matter for people who buy and later sell. If a registered holiday home changes hands other than by inheritance, for example by sale or gift, the Department cancels the register entry and certificate, and the new owner must apply afresh and cannot run the unit as a holiday home until that is done. If an owner dies, the heirs must file a notice with a death certificate within 30 working days, and further steps follow once the estate is administered; if they miss the deadline, the register entry, certificate and permit lapse by operation of law. A rental programme that a developer attaches to a unit is therefore tied to the owner who is on the register, not to the unit.
What a Holiday Home Must Provide and Record
The Law sets physical conditions in article 5. Each holiday home must be an independent unit with its own space and an independent entrance and exit. It may have at most five bedrooms and house at most ten people. It needs a kitchen equipped so that guests can prepare their food and wash up, and a waste container in the garden of the property. Bedrooms are arranged for no more than two people each, apart from young children who need a parent or guardian. For up to six users the unit needs one bathroom and one toilet; for seven to ten users it needs two bathrooms and two toilets. Minimum standards beyond these are left to a regulation, so a unit can meet the conditions in the Law and still be asked to meet additional rules once the regulation is published.
Operating duties are listed in article 10. The owner must hand the unit over according to the booking agreement, display warning notices in English as well as Turkish, and have the unit cleaned between users. Unless the parties agree otherwise, a booking starts at 14:00 and ends at 12:00 noon on the next day. The owner must display a smoke-detector notice where detectors exist, a camera notice where cameras cover the common areas or the building exterior, a notice marking each parking space as belonging to the building, and the building address on the waste container. An inventory of the furniture and equipment must be placed where the user can see it, and a bilingual information notice from the Law’s annex must be posted. Article 12 gives the owner defined rights: a day’s charge is calculated as if the user spent the whole arrival day in the home, an overstaying user may be removed with luggage unless a written contract proves a later date, and the owner can claim damage from a deposit or, failing that, from the user.
Records go to the authorities. The owner must have each user complete and sign the user registration form and must submit two copies of the forms to the Department within ten working days after the end of each month, or through the electronic portal if the Department asks for that. The Department forwards one copy to the police within three working days and keeps the other for at least 90 working days. If the owner learns that a user or companion has an epidemic disease, the Law requires notice to the Department, the police or the health ministry. The Department monitors registered homes whenever it chooses and must inspect them at least once every three years.
| Stage | What the Law provides | Amount at the current wage of TL 70,893 |
|---|---|---|
| Notice of breach of listed duties (arts. 5 and 10) | Written notice giving 15 working days to put it right | None |
| Administrative fine if not corrected | One monthly gross minimum wage, payable within 15 working days | TL 70,893 (about GBP 1,064) |
| Fine unpaid after 15 working days | The fine doubles; if still unpaid and uncorrected, the permit is suspended and the door is sealed | TL 141,786 (about GBP 2,128) |
| Offence: running without registration, certificate or permit | Fine on conviction of up to 10 times the monthly gross minimum wage | Up to TL 708,930 (about GBP 10,639) |
| Offence: unpaid permit fee, breach of the user form or monthly return duties, breaking a seal | Fine on conviction of up to 5 times the monthly gross minimum wage | Up to TL 354,465 (about GBP 5,320) |
The fine arithmetic is simple: 70,893 x 2 = TL 141,786 for the doubled administrative fine, 70,893 x 10 = TL 708,930 for the top criminal band, and 70,893 x 5 = TL 354,465 for the lower band. These are maximum levels for courts, and the Law says “up to”; the table does not predict what a court would impose. The Department can also cancel the register entry and close and seal a home if, after it was approved, the owner changes or removes furniture and fittings so that it loses the qualities required, and does not restore them within 30 working days of a written request.
Rental Income Tax for Renting Out Property in North Cyprus
Income from renting immovable property is taxed by withholding under article 31(6) of the Income Tax Law, in the text consolidated on 25 May 2026. Ten per cent of the gross rent that accrues is paid to the Tax and Revenue Department by the owner or the owner’s representative. The gross figure includes rent taken in advance, and the rule applies whether the property is let furnished, or with installations and fixtures, or bare. For individuals, and for companies whose only activity is renting out property, the tax withheld in this way is the final tax for the year: the rent is not added to other income, expenses of earning it cannot be deducted, and the tax paid cannot be refunded or set against other taxes.
A worked example shows the mechanism. Take a rent of GBP 600 a month; the figure is a round number chosen for the arithmetic and is not a market rent. Ten per cent withholding is GBP 60 a month, or 60 x 12 = GBP 720 over a year. If the tenant pays three months in advance, that is GBP 1,800 of rent received, and the withholding on it is 1,800 x 10% = GBP 180. The tax is calculated on the rent whatever costs the owner bears, because the law excludes the deduction of expenses against this income. The law also keeps the loss rule narrow: if rent is not collected, the owner notifies the Tax Department, and once the Department confirms it, or the dispute is in court, the tax is due when the rent is actually collected.
Several details move the result. First, an exemption applies if the total monthly rent is below the monthly minimum wage in force and the person proves no other taxable income; the person must obtain the Tax Department’s approval at the start of each tax period or in the month the contract is made, whichever comes first. With the minimum wage at TL 70,893 from 1 July 2026, that threshold is about GBP 1,064 at the October rate of 66.6323. Second, the paragraph that gives residents a monthly share of the annual allowance does not apply to people who are not settled in the TRNC. Third, where the owner lives abroad and has no permanent representative in the TRNC, article 33(2) makes the person paying the rent responsible for calculating the 10% and paying it to the Department. Fourth, where a property forms part of business, professional or farming accounts, article 31(6)(D) takes it out of the final-tax rule and the rent is assessed with the rest of the business income.
Withholding does not remove the paperwork. Paragraph (F) of the same article states that taxation on this basis does not cancel the duties to obtain and issue the documents required by the Tax Procedure Law, or the duty to file the annual return. The annual return is due in April for the previous calendar year under article 26(1). Article 52 gives a 5% reduction in the tax payable to those who have filed their monthly returns on time and paid the tax on time for 36 months, provided no additional tax has been assessed in the period. The statute fixes the 10% rate and the duty to pay; the form and the filing calendar for the monthly withholding return are set by the Tax Department.
Separately, income tax on a resale gain and the land registry fees on a later sale follow different rules, which our guide to North Cyprus property taxes and fees sets out with a worked purchase example.
Other Taxes and Costs When Renting Out Property in North Cyprus
Withholding is only one line in an owner’s costs. The table lists the others that appear in the TRNC texts, with the rate and its source.
| Item | Rate or amount | Source and note |
|---|---|---|
| Stamp duty on a lease | 0.5% (binde bes) of the total fixed-term rent; for foreign-currency amounts the official effective selling rate on the stamping date is used | Stamp Duty Law 19/1963; the tenant pays unless otherwise agreed |
| VAT on renting immovable property | 0% | VAT regulation, Schedule I, updated 7 October 2026 |
| VAT on appliances | 5% on cookers, ovens, fridges, freezers, washing machines, dishwashers, microwaves, televisions and inverter air conditioners | VAT regulation, Schedule II |
| VAT on furniture and soft furnishings | 10% on wooden and metal furniture, spring mattresses, bedding and curtains | VAT regulation, Schedule III |
| Annual immovable property tax | For reinforced-concrete housing, TL 6.60 per m2 up to 120 m2 and TL 7.15 per m2 above, with surcharges of 10% to 60% by category and a 15% reduction for buildings from 2000 or earlier | Schedule effective 1 January 2025, the latest the Tax Department site shows |
| Tax on insurance premiums | 5% of the premium in the policy | Financial Transactions Tax Law 62/2026, in force 1 October 2026 |
| Tax on currency exchange | 0.1% of the foreign-currency sale amount | Same law; collected through financial institutions |
The stamp-duty arithmetic uses the same example. A 12-month lease at GBP 600 a month states a total rent of 600 x 12 = GBP 7,200, and 0.5% of that is GBP 36, converted into lira at the official rate on the stamping date. The property-tax figures also work out simply. A 75 m2 apartment pays 75 x TL 6.60 = TL 495 at the base rate, TL 544.50 with a 10% surcharge and TL 792 with a 60% surcharge, which is roughly GBP 7 to GBP 12 at 66.6323. The 2025 schedule is the latest the Tax Department site shows; if a 2026 schedule has been issued, the amounts will differ.
Currency matters because the lira is the TRNC currency and a lira rent loses value quickly. The Statistical Institute reports that consumer prices rose 35.02% in the twelve months to September 2026 and 28.15% between December 2025 and September 2026. The Foreign Exchange Law 38/1997 allows contract amounts to be expressed in foreign currency, and allows remittances in and out of the country in foreign currency through banks, provided the names and addresses of sender and recipient are recorded and totals are reported to the Central Bank. Most listings on our site show sterling, so many owners agree rent in sterling or euros; whether a tenant agrees to that is a matter for the contract.
Buyers also meet the 2026 changes. Land Registry fees for foreign buyers under the schedule in Resmi Gazete 197 of 7 October 2026 are valid until 5 January 2027, and they affect the cost of buying a unit that will later be let; the same applies to the acquisition limits under Decree-Law 89/2026. Our guide to whether foreigners can buy property in North Cyprus explains the cap of three apartments (six for nationals of states that recognise the TRNC and grant the same right) that limits how many units a foreign owner can hold under the decree, which bears directly on any plan to let several flats.
Long-Term Tenancies: Contracts, Control Areas and Eviction
For a tenancy longer than 60 days the contract carries most of the weight. The Rent (Control) Law 17/1981, as amended up to 27/2011, is the main statute on tenant protection. It does not apply across the whole TRNC: under article 3 it applies to residences and workplaces inside areas that the Council of Ministers declares as control areas by a decree published in the Resmi Gazete, and the Council can exempt a class of premises or revoke a declaration. A first question for a long-term let is therefore whether the property lies in a declared area. The text used here is a Northern Cyprus law office’s reproduction of the consolidated law, so the current Resmi Gazete decrees are the reference for which areas are declared.
Inside a control area the Law protects a “statutory tenant”, meaning a tenant who stays on after the contract ends. Under article 7, an eviction order can be made only on listed grounds. They include rent unpaid for a week after it falls due, with the offer of payment by registered post counted as an offer; breach of other tenancy obligations; behaviour that disturbs neighbours or use contrary to law or morality; damage to the property; termination by the tenant’s own notice; sub-letting or taking a lodger for gain; the landlord’s reasonable need of the property for the landlord, a spouse or an adult child; demolition or alteration with the permit in hand and at least one month’s written notice; and expropriation or development projects. The court may suspend or postpone the order for up to three months on conditions. Under article 6, if the parties cannot agree a new rent after a contract has ended, either may apply to the court, which considers factors such as the building’s age, cost, location, condition and comparable rents, and fixes a reasonable rent that takes effect from the date of the application.
A written lease for a fixed term normally covers a short list of points, and the TRNC texts make some of them concrete.
- The parties and the property: the title (koçan) details and the unit number, so that the tenant can be tied to a unit that the Land Registry shows as the owner’s.
- The term, the rent, the currency and the payment date, with the one-week default period of article 7 in mind for controlled premises.
- Who pays stamp duty on the lease (the Stamp Duty Law places it on the tenant unless agreed otherwise) and the withholding position, particularly if the owner lives abroad and the tenant becomes the party that must calculate the 10%.
- An inventory signed by both sides, as the Holiday Houses Law requires for short stays, and a list of the utilities and who holds each account.
- Repairs, access and a procedure for ending the lease, including the notice period.
Local lawyers and accountants can state how courts treat deposits and notices in practice, and the guide does not substitute for that; the aim here is to show which parts come from statute and which depend on the signed paper.
Tenant Types: Students, Residents and Holiday Guests
Students form the group most often named in connection with Famagusta. According to the Statistical Institute’s Statistical Yearbook 2024, the Eastern Mediterranean University (EMU) enrolled 15,729 students in 2024-25, down from 16,640 in 2021-22, a fall of 5.5%. Total higher-education enrolment in the TRNC went from 114,000 to 104,873 over the same period, a fall of 8.0%. The municipality of Famagusta lists four other universities in the city besides EMU: Istanbul Technical University North Cyprus Campus, Ada Kent University, Cyprus West University and European Leadership University, with 2024-25 enrolments of 1,209, 1,213, 372 and 1,212. Adding EMU gives 15,729 + 1,209 + 1,213 + 372 + 1,212 = 19,735, which is consistent with the municipality’s statement that more than 20,000 students and staff live in the city for most of the year.
| Measure | Figure | Source |
|---|---|---|
| EMU enrolment, 2021-22 to 2024-25 | 16,640 to 15,729 (-5.5%) | TRNC Statistical Yearbook 2024, table D10 |
| All TRNC higher-education enrolment, same period | 114,000 to 104,873 (-8.0%) | TRNC Statistical Yearbook 2024 |
| EMU on-campus dormitories | 19 complexes with about 10,000 places; new students have priority | EMU Information Handbook 2024 |
| Students in five Famagusta universities, 2024-25 | 19,735 (sum of the five enrolments) | Yearbook figures with the municipality’s list of universities |
| Dwelling units given final approval in Famagusta district, 2025 | 1,492 (538 urban and 954 rural) | Statistical Institute, Construction and Parcel Statistics 2025 |
The dormitory figures give a rough sense of how demand reaches private housing. EMU’s handbook says its 19 complexes house about 10,000 students and that new students get priority; students may also rent flats or rooms privately. If all 10,000 places went to EMU students, 15,729 – 10,000 = 5,729 students, or 36.4% of enrolment, would be outside the dormitories. That is simple subtraction, not a count of renters: some students live with family, and some dormitory places serve students of other institutions. On the supply side, 1,492 dwelling units received final approval in Famagusta district in 2025, according to the Statistical Institute’s bulletin, which counts completions and not sales or rents. Together these figures describe a market in which enrolment has declined while new housing continues to be completed, and they are the reason this guide makes no statement about the rent a student unit will earn.
Holiday guests are a different group. Trade press citing TRNC tourism data reported on 20 July 2026 that the TRNC received 2,589,729 visitors in 2025 against 2,208,855 in 2024, an increase of 380,874, or 17.2%. These are visitor arrivals, not bed-nights, and the reports do not break them down by type of accommodation, so they say nothing on how many guests stay in private holiday homes. The Holiday Houses Law’s own purposes clause, which refers to tracking tourists and statistics, points to the data that registration is meant to produce. Residents and workers on longer tenancies form the third group; for them the points above on control areas, stamp duty and currency apply, and a lira rent faces the inflation described earlier.
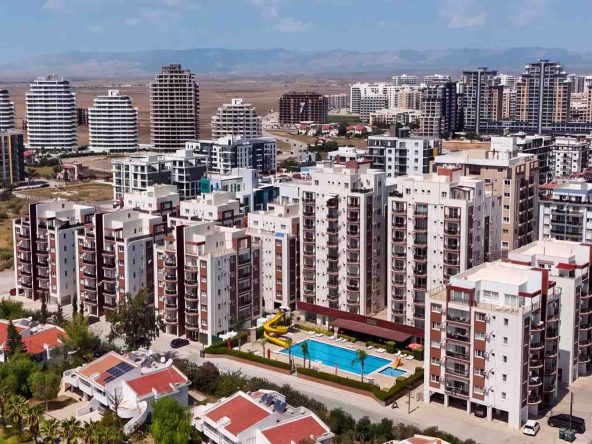
Location affects which group is realistic. Listings in Famagusta city, such as Sky Sakarya and Angel Towers, sit in the university city. Esentepe schemes such as Moonlight Villas are marketed by the developer as holiday homes. Our Northern Cyprus country page lists every town we cover, and the Famagusta and Esentepe city pages list the current properties in each town, and the town-by-town guide to places to buy in North Cyprus compares the districts on access, hospital and character.
Furnishing, Inventory and Management Companies
For holiday lets, the Law makes furnishing partly a legal matter. The class (standard, comfortable or top class) depends on the services, furniture and equipment, the unit needs a working kitchen, the inventory must be on display, and the owner must keep the equipment working for guests. For longer lets nothing in the texts sets a furnishing standard, so what is included is whatever the contract lists. The VAT regulation’s treatment, described in the cost table, gives appliances 5% and furniture 10%, so a furnishing budget carries VAT even though the rent itself is on the 0% schedule.
A management company can act in two legal ways under the Holiday Houses Law. It can act as an agent under a written power of attorney, in the owner’s name and on the owner’s account, or it can register the owner’s units under its own name with the owner’s written consent and run them. In both cases the owner remains the person whose title the Department checks, and the register entry follows the owner’s title. The statutory duties listed above, such as user forms, monthly returns, notices and fines, fall on the “owner or attorney or lessor”, so a management contract is where the owner records who performs each duty and who bears a fine.
| Item in the management agreement | Why the text of the Law or tax rules makes it relevant |
|---|---|
| Which party registers the unit and holds the certificate and permit | Articles 7-9: the register entry and permit are tied to the named owner or lessor, and a sale cancels the entry |
| Who pays the annual permit fee | Article 9: the fee is due every year per unit, at 7%, 11% or 15% of the monthly gross minimum wage by class |
| Who completes the user forms and files the monthly returns | Articles 10(10), 11 and 13: two copies to the Department within ten working days after each month; a breach is an offence |
| Who withholds and pays the 10% income tax | Income Tax Law art. 31(6): payable by the owner or representative; art. 33(2) places it on the payer if the owner is abroad without a representative |
| Fee basis and what it covers | The texts set no management fee; the contract decides whether the fee is a percentage, a fixed sum, and whether it is before or after tax |
| Cleaning between guests, maintenance, replacement of items | Article 10(3) and (4): cleaning between users and working equipment are owner duties |
| Handling of the damage deposit | Article 12(3): the owner may claim damage from the deposit or the user |
| Insurance and who holds the policy | A premium carries the 5% transactions tax; the policy terms are set between insurer and policyholder |
| Termination and handover of records | The Department keeps copies of user forms for at least 90 working days; the owner’s own records stay with the owner |
None of the texts sets a management fee or approves a standard form, so the percentages that appear in management offers come from the offer itself. A buyer reading an offer can check the items above against the table and ask where each is written. For off-plan and resale buyers, the guides on buying off-plan in North Cyprus and how to buy property in North Cyprus step by step explain when a registered sale contract exists, which is the document the Holiday Houses Law form asks for when the title has not yet passed.
Rental Guarantee and Rental Management Claims on Developer Pages
Developer pages for North Cyprus projects use several phrases about letting: “rental guarantee”, “rental management”, “whole year renting” and “professional rental management system”. None of these is a legal term in the TRNC texts, and a page that contains one does not state a return unless it gives a figure, a base, a period and an obligor. The listings on our site show the range. The table records what each listing page says, as at 24 October 2026, and what it leaves out; prices are shown as the listing pages display them.
| Listing | What the listing page says about letting | What the page does not state |
|---|---|---|
| Isatis 4, Famagusta (price on request) | The developer says “a two-year rental guarantee at 6% will be offered to customers” | What the 6% applies to, whether it is annual, who pays, conditions, or a completion date |
| Isatis 5, Famagusta (price on request) | The same two-year, 6% sentence | The same terms; no completion date or unit count |
| Caesar Blue, Boğaz | The projects page lists “Rental Guarantee” as a bullet beside a 30% down payment and up to 36 months interest-free; the group runs a holiday-booking site | Any term, return, period or payer; no current price (an archived penthouse figure from 17 January 2024 was “starting from” GBP 315,103) |
| Caesar Palm Jumeirah, Boğaz (price on request) | An April 2023 presentation mentions a rental guarantee in two of three payment options | Terms, a named guarantor or an end date |
| Caesar Resort, Iskele (price on request) | “Opportunity for whole year renting”; the group’s booking site showed archived nightly rates of GBP 45-90 (2023) and GBP 55-100 (2024) | Programme terms, a management company or a service-charge budget |
| Bahamas Homes, Esentepe (from GBP 94,950) | The developer says rental management is optional and no fixed return is provided | A fee, a rent figure or an operator |
| Moonlight Villas, Esentepe (resale only, price on request) | Designed as a holiday home; rental management is offered; the FAQ says rental income is not assured | A fee, a rent figure or what is furnished |
| Mykonos Homes, Esentepe (resale only) | Optional rental management; the developer’s FAQ says no returns are assured | A fee, a rent figure or furnishing |
| Pearl Island, Esentepe (projects page: from GBP 220,000) | Management offered, no fixed return stated | A rent figure or whether the studios are furnished |
| Sky Sakarya, Famagusta (resale asks from GBP 63,500) | The developer says “a professional rental management system is fully operational in the building” | Fees, terms or occupancy data |
The first two rows show how much a short sentence can hide. Suppose a unit costs GBP 100,000; the figure is only for arithmetic, since the Isatis pages show no price. If “6%” means 6% a year for two years, the benefit is 100,000 x 6% x 2 = GBP 12,000. If it means 6% once over the whole two years, the benefit is GBP 6,000. If it applies to a different base, such as the first-instalment amount, the figure changes again. A page that says “two-year rental guarantee at 6%” fits all of these readings, which is why the sentence cannot be treated as a return until the contract defines it.
Several features of a binding guarantee can be read from the paper. A binding guarantee names the obligor as a legal entity, not a brand. It states the base (price paid, price in the contract, or amounts actually paid so far), the payment dates and the conditions for stopping, including what happens if the unit is not handed over on time. The Caesar Palm Jumeirah presentation, for example, shows 24% of the price “covered by the rental guarantee over three years” in one option, which is a way of financing the purchase and not a rent, and the guide on the listing itself warns that such a line must appear in the signed contract with a named obligor and the conditions under which it can end. The Holiday Houses Law adds a separate point: a rental programme that places the unit with a booking platform is a holiday letting, and the registration, permit and monthly returns apply in the same way as for a private owner.
Developers’ own disclaimers vary. Cyprus Constructions pages for Bahamas, Mykonos and Pearl Island say management is optional and that no fixed return is provided. Afik pages for Caesar Blue and Palm Jumeirah carry the word “guarantee” in marketing material without terms. These are statements by the developers, quoted on our listing pages, and they are not assessed here. The guide to North Cyprus property prices covers how to read “from” prices, resale asks and “on request” figures that appear in the same listings.
Insurance, Residence Permits and the 2026 Decree
Insurance for a let property is a contract between the owner and an insurer. The Holiday Houses Law does not list a liability policy among the conditions of registration. What the texts do show is the cost of the premium: the Financial Transactions Tax Law 62/2026 taxes insurance transactions at 5% of the premium in the policy, from 1 October 2026. For a premium of GBP 300, the tax is 300 x 5% = GBP 15. A management agreement, a mortgage or a developer’s service-charge system may separately require cover, and the policy wording shows what counts as a covered loss when a guest, not the owner, causes damage. The owner’s statutory right to claim damage from a deposit or from the user under article 12(3) works alongside any policy, not instead of one.
Residence permits interact with letting in one respect. The property-based short-term residence permit in article 14(2)(b) of the Residence and Visa Regulation, in the text of 5 October 2026, requires a home suitable for residence that is used for it. With title in the applicant’s name and total property value of GBP 300,000 or more, the permit runs for 10 years; below GBP 300,000 it runs for 5 years. With only a stamped and approved sale contract, GBP 300,000 or more gives 5 years, and below that, proof of regular monthly income of one minimum wage is needed. A purchase does not itself grant a permit; it is a separate application. Whether a unit that is let to others for most of the year meets the “used for residence” wording is a question for the immigration authority.
The 2026 decree reaches holiday lets in two places. Under Decree-Law 89/2026, units that exceed a foreign buyer’s legal acquisition right and are placed under the holiday-homes legislation receive a use certificate of unlimited duration while they remain registered, and a “licensed intermediary investor” who cannot transfer homes to buyers within two years of final approval must place them under the holiday-homes rules or lose the licence. Both rules depend on the decree remaining in force. It is a Council of Ministers decree published in Resmi Gazete 147 on 7 August 2026, with a 90-day validity that ends about 5 November 2026 unless Parliament enacts it; the consolidated Law 52/2008 on the legislation site still shows the stricter earlier text. The position after that date depends on whether Parliament has enacted it. Our guide to the north and south Cyprus property rules compared and the Cyprus villas guide set out the Republic of Cyprus regime, where short-term lets are licensed by the Deputy Ministry of Tourism, a separate system that does not apply to a unit in the north.
Title also decides whether a let is lawful in the way an owner expects. Registration needs the title copy and the final approval certificate, so a unit whose title category or permits are unclear cannot be registered cleanly. The guide to the North Cyprus title deed check covers the categories and the Land Registry search, and the guide on the risks of buying in North Cyprus covers pre-1974 property claims, which are a title matter and not a tenancy matter.
A Pre-Letting Checklist for Renting Out Property in North Cyprus
The steps below put the texts in sequence. Each item names the document or office, so that an owner can tick it off; the order follows how the requirements arise.
- Confirm the owner on record: obtain a Land Registry ownership search (araştırma belgesi) at the district Land Registry office and check that the title (koçan) or registered sale contract names the person who will let.
- Decide the letting model by length: a stay of up to 60 days is a holiday let; a longer stay is a tenancy. A unit can follow one model, or the owner can use each at different times of the year, provided the holiday-let paperwork is in place for the short stays.
- For holiday lets, collect the title copy, the final approval certificate, any registered sale contract, identity documents and, if an agent or company lets the unit, the owner’s notarised consent or power of attorney.
- Check the unit against article 5: independent entrance, at most five bedrooms and ten users, an equipped kitchen, the right number of bathrooms and toilets, and a waste container.
- Apply to the Tourism Planning Department, through the portal if it asks for one, and calendar the 15, 30, 90 and 10 working-day periods in the Law.
- Pay the certificate and permit fees at the Tax Department revenue counter, and diary the permit renewal for the 30 working days before the year ends.
- Put the notices, the inventory and the signage in place before the first guest, in Turkish and English.
- Set up the monthly return of user forms, and decide who files it.
- For any let, agree the currency, the withholding and who pays stamp duty, and have the lease stamped at the Tax Department.
- If the owner lives abroad, name a permanent representative or agree how the tenant will calculate and pay the 10%; file the annual return in April.
- Take out insurance on terms that match the use, and keep the policy and inventory with the lease file.
- When the unit is sold, remember that the holiday-home register entry is cancelled on sale and the buyer must apply again.
Sellers and buyers of units with sitting tenants can use the same list in reverse: a buyer asks for the register entry, the latest permit, the last twelve months of user forms or the stamped lease, and the proof that withholding was paid.
Frequently Asked Questions
Is a licence needed for renting out property in North Cyprus?
For a tourist stay of up to 60 days, yes. Under the Holiday Houses Law 54/2025, in force since 1 March 2026, the owner or lessor needs a registration certificate and an operating permit from the Tourism Planning Department, and the permit is renewed every year. A tenancy longer than 60 days is outside that Law, but the rent is still taxed and the lease is stamped.
How is rental income taxed when renting out property in North Cyprus?
Ten per cent of the gross rent, including advance rent, is withheld and paid to the Tax and Revenue Department under article 31(6) of the Income Tax Law. For individuals it is the final tax on that income, expenses are not deducted, and the annual return is still required. If the owner is abroad without a representative in the TRNC, the person paying the rent is responsible for the withholding.
What happens if a holiday home is let without registration?
Running a holiday home without a register entry, certificate or permit is an offence with a fine of up to 10 times the monthly gross minimum wage, which is up to TL 708,930 at the TL 70,893 wage from 1 July 2026. The Department can also seal the home. Breaches of listed duties first lead to a notice and then to a fine of one monthly minimum wage.
Can a foreign owner use the same rules when renting out property in North Cyprus?
Yes. For renting out property in North Cyprus, the Holiday Houses Law and the Income Tax Law apply to owners whatever their nationality, and the digital system is reported to be open to Turkish and foreign individuals. What differs for non-residents is that the deductions for settled residents are not available and that, without a representative in the TRNC, the tenant must pay the withholding.
Does a rental guarantee in a developer’s brochure mean assured income?
Not by itself. In renting out property in North Cyprus through a developer’s programme, the phrases on the developer pages in our listings, such as “a two-year rental guarantee at 6%”, give no base, period or obligor. The contract has to name the party that pays, the amount and its base, the dates and the end conditions. The Cyprus Constructions pages state that management is optional and that no fixed return is offered.
Are students a reliable tenant group in Famagusta?
For renting out property in North Cyprus to students, the official figures do not support a simple answer. EMU enrolment fell from 16,640 in 2021-22 to 15,729 in 2024-25, and its 19 dormitory complexes hold about 10,000 students. Rent depends on the unit, its distance from the campuses and the lease terms, and the figures above describe demand drivers, not a rent.
Does VAT apply when renting out property in North Cyprus?
For renting out property in North Cyprus, renting immovable property is on the 0% schedule of the VAT regulation updated on 7 October 2026. Accommodation services linked exclusively to tourism are on the 5% schedule, and the regulation does not mention holiday houses, so the classification of a holiday-home stay is a matter for the Tax Department. Furniture bought to fit out the unit carries 10% and appliances 5%.
Does the lease have to be stamped?
A lease signed when renting out property in North Cyprus is taxed under the Stamp Duty Law as an agreement on the total rent of a fixed term. The rate in the schedule is 0.5%, so a 12-month lease at GBP 600 a month, a total of GBP 7,200, carries GBP 36 of duty. The tenant pays unless the parties agree otherwise, and foreign-currency amounts are converted at the official effective selling rate on the stamping date.
Can an owner evict a tenant at the end of the lease?
In a control area declared under the Rent (Control) Law 17/1981, an eviction order can be made only on the grounds listed in article 7, which include rent unpaid for a week after it is due and the landlord’s reasonable need of the property. Outside declared areas that Law does not apply, so the contract and the general law govern. A lawyer registered in the TRNC can confirm whether the property lies in a declared area.
What happens to the holiday-home registration when the property is sold?
The Department cancels the register entry and certificate on a sale or gift, and the new owner must register again and cannot run the unit as a holiday home until that is complete. If the owner dies, the heirs must notify the Department within 30 working days; otherwise the registration lapses.
Last checked: 24 October 2026. Sources: Holiday Houses Law 54/2025; Income Tax Law, consolidated 25 May 2026; Stamp Duty Law 19/1963; VAT regulation, 7 October 2026; Tax Department, minimum wage from 1 July 2026; Cyprus Turkish Chamber of Commerce, minimum wage 2026; TRNC Central Bank exchange rates; Financial Transactions Tax Law 62/2026; Immovable property tax schedule 2025; Foreign Exchange Law 38/1997; Residence and Visa Regulation, 5 October 2026; Resmi Gazete 147, 7 August 2026; Resmi Gazete 197, 7 October 2026; Rent (Control) Law 17/1981, law office reproduction; Kıbrıs Gerçek, 24 November 2025; Yorum Kıbrıs, 24 July 2026; TRNC Statistical Yearbook 2024; Construction and Parcel Statistics 2025; Consumer Price Index, September 2026; EMU Information Handbook 2024; Famagusta Municipality; Turizm Günlüğü, 20 July 2026.